
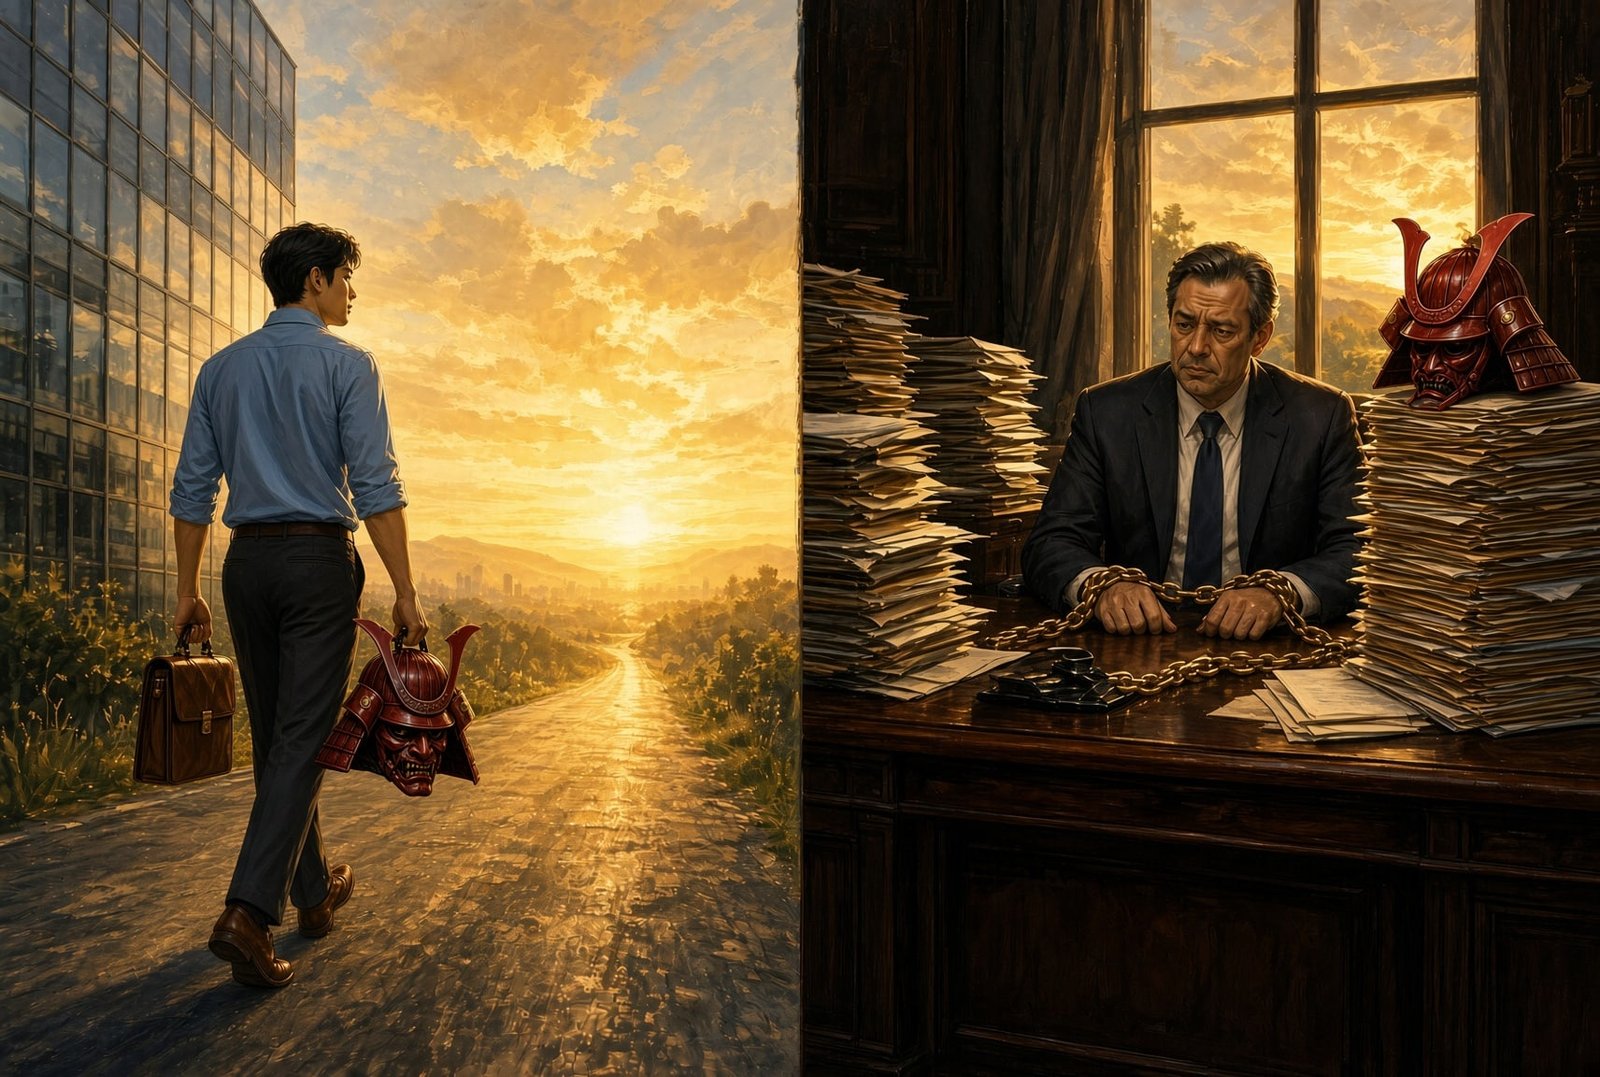
In 2012, two months before my 35th birthday, I engineered my layoff from a 13-year career in investment banking. At the time, it felt like the riskiest thing I had ever done. Was I really going to blow up my career right as my earning power was about to compound?
It did not seem wise. And if I could do it over again, I probably would have worked five more years until 40 to save and invest more. To extend the drudgery, I would have pushed harder to relocate to another city and turn the last stretch into an adventure.
But now that I’m 14 years into FIRE and almost 50, I’ve had a change of heart. Retiring at 35 is not nearly as risky as it feels in the moment. Nor is the path to get there as hard as it sounds — saving and investing over 50% of your income for 13 years after college, or 17 years after high school, is doable when you’re young and have few obligations.
If things don’t work out after one to three years at age 35, you can always go back to work and find another soul-sucking job that makes you question your purpose in life every single day. Turns out grinding 60 hours a week is a surprisingly effective spending deterrent.
Two Friends Who Proved The Downside Was Small
One friend retired from banking at 33 to become a baker. She had to wake up at 6am and get yelled at by the head chef daily. She figured that if she was going to get yelled at either way, she might as well get yelled at in finance and make 8X more. So she returned a few years later, despite having a portfolio worth about $2 million to live off.
Another friend wanted to be a photographer. She was at Facebook making about $300,000 a year, but she couldn’t stomach what the algorithm was doing to kids’ brains. So she left and freelanced for a year. The money was terrible, but she had savings and went off to explore Cambodia, Taiwan, Vietnam. She actually saved money while abroad because the cost of living is so much lower.
After a year, she realized she couldn’t make it as a professional photographer and went back to big tech for the big bucks. The money was just too good to ignore, despite having enough. Kids be damned!
Both friends were in their early-30s. Both found work two years of taking their leap of faith to experience FIRE and following their passions. Neither of them is on the street.
Retiring At 50 Is Brutally Hard Because Of What You Have To Lose
I’m in the last year of my 40s, and I feel melancholy that time went by so quickly. I would give up almost everything to rewind time by a decade.
If I were still in finance today, I’d be strategizing right now on how to negotiate a severance and collect all my deferred compensation next year at 50.
But frankly, I don’t know if I’d be able to pull the trigger based on what’s in front of me.
With 15 more years of work experience, I assume I’d have made Managing Director by now. That means a base salary of around $500,000, plus a discretionary bonus somewhere between $0 and $2 million for the average MD.
Walking away from potentially $2.5 million in total compensation is much harder than walking away from $500,000, even after adjusting for inflation. The golden handcuffs don’t loosen with time. They tighten.
Lifestyle Inflation Is The Real Handcuff
If I had been making $1 million a year on average for a decade, my lifestyle would have inflated to match. Bigger house. Two kids in private school. A stay-at-home spouse. Hiring gardeners, house cleaners, trainers, and maybe even chefs. Because why not? I’m bringing home the toro sashimi.
The pressure to keep providing for that life would be enormous because there’s also university tuition coming up and the desire to create multi-generational wealth. Trying to fund it without a W-2 income and the possibility of a big bonus would feel almost impossible.
When people depend on you, the instinct is to grind harder, not less.
This is partially why I’m so fascinated by the rise of stay-at-home boyfriends and stay-at-home husbands who don’t work at all. I would have thought the desire to provide was baked into every man’s DNA. Guess not.
Rewind To 34, When I Had Almost Nothing To Lose
Now let me rewind to when I was 34 and plotting my escape.
At the time, I had no children and a working wife. I wasn’t providing for her or for two little ones.
Both of my parents were healthy, alive, and recently retired with government pensions. I felt zero stress about coming up with $10,000 to $20,000 a month for elder care.
I was also only two years into writing Financial Samurai, which I felt had tremendous upside. There were no bloggers writing about finance who had actually worked in finance. All of them were focused on budgeting and saving instead of pushing readers to earn and invest more.
It’s still rare today. The few finance people who do write about personal finance are usually still working at an RIA or a fund, using the content to attract customers. So it’s not really geared toward the FIRE community.
Most importantly, at 34 I knew I could get back into finance within a year or two if I needed the money. I also knew I could land some lower-level finance role at a tech startup if I really wanted to. The downside risk of not finding work was low.
At 50, The Job Market Doesn’t Want You Back
At 49, it is far harder to find a well-paying job in this economy once you lose one.
AI has compressed the demand for knowledge workers. And at 50, there are simply fewer roles available at your level of experience and comp than there were in your 20s and 30s.
So if I fired at 50, I would need to be absolutely certain I was never coming back. The boats would be burned. No alternative but to live off investments and earn some side hustle money if needed.
That certainty is a much heavier thing to carry at 50 than the casual “eh, I’ll figure it out” you get to say at 34.
Example Of FIRE At 35 vs FIRE At 50
| Description | Retiring at 35 | Retiring at 50 |
|---|---|---|
| Comp you’re walking away from | ~$150,000 | ~$350,000 |
| Dependents | Usually none | Kids, spouse, aging parents |
| Ability to get rehired | High, within 12 months | Low, and at lower pay |
| Lifestyle inflation | Minimal | Fully baked in |
| Years of expenses to fund | 50+ | 35+ |
| Regret if it fails | Lost a year or three | Lost your last high-earning decade |
| Emotional difficulty | Feels terrifying, is manageable | Feels rational, is nearly impossible |
FIRE Gets Harder As You Age, Not Easier
Conventional wisdom says that as you age and build wealth, retiring early gets easier. I’m no longer sure that’s true.
The older and wealthier you get, the more you have to lose.
You also accumulate responsibilities. If you have a family, you carry more concern for your children than you ever did for yourself. Given the economy and the direction AI is heading, you naturally start thinking about generational wealth so your kids will be OK even in the worst-case scenario.
Unfortunately, FIRE makes building generational wealth harder, not easier. Do you really want to be that selfish to only think about your own freedom when your children will graduate school in an economy that does not welcome them?
Right now, because I have no realistic employment options, the path of least resistance is to stay retired. Ironic, but true.
Back in 2023, I did work part-time at a fintech startup for four months. It was a good experience that boosted my confidence that I could get hired again if I really wanted to. But that clock is now expiring, as that was three years ago.
That same four months also reminded me exactly why I left in the first place. I’m not built for meetings, commuting, and giving up my time for someone else’s dreams.
But I’ll admit it. After buying my house and living paycheck to paycheck for six months, it felt really good to have steady active income again. If I’d been making two to five times that amount, leaving would have been way too hard.
Being Honest About Your FIRE Odds
The conclusion I’ve come to: if you want to FIRE, do it young (under 45). It’s easier to pick yourself up off the road after getting hit when you’re young and still have Wolverine-level regenerative powers. After 45, the recovery just isn’t the same.
If you can, take a paid two or three month sabbatical to test the waters first. A one month sabbatical is simply not long enough to give you a real taste of what retirement is actually like. Besides, the first month of a sabbatical is usually paid, which can give you a false sense of security.
If I were sitting in a Managing Director seat today with two young kids at home, there’s maybe a 20% chance I’d muster the courage to negotiate a severance and walk.
The other 80%? I’d tell myself to suck it up and grind at least until my youngest graduated high school in 2038. My daughter is six, so that’s 12 more years. I’d be 61.
And being honest with myself, I’d probably feel pressure to work four more years to cover college too. The most expensive private universities will cost over $160,000 a year in tuition alone by then. So call it 65.
That’s not early retirement. That’s just retirement.
Hence, the best time to take the leap is the moment it scares you most, not the moment it finally feels safe. Because if you wait for absolute certainty, you’ll never take that leap of faith.
Reader Questions
Do you think it’s harder to retire early at 35 or at 50? Have your golden handcuffs gotten tighter as your income has grown?
For those of you who left a high-paying job in your 40s or 50s, what finally pushed you over the edge? And for anyone who went back to work after retiring early, was the return easier or harder than you expected?
Finally, if you’re a parent, has having children made you more likely to keep grinding or more determined to get out?
Negotiate an Exit
If you’re thinking about leaving a job you no longer want, don’t quit. Get laid off instead. Negotiating a severance is what gave me the financial runway and the peace of mind to walk away in 2012 with deferred compensation plus a six-figure check. Pick up a copy of How To Engineer Your Layoff to learn how to negotiate a severance yourself. Use code “saveten” to save $10 at checkout.

Subscribe to The Financial Samurai Newsletter
If a friend forwarded you this post, join 60,000+ readers and subscribe to the free Financial Samurai newsletter at https://www.financialsamurai.com/news. You can also sign up at https://www.financialsamurai.com/email to get new posts the moment they publish, ad-free for the first few hours.
Everything I write is based on firsthand experience since 2009, because money is too important to be left up to pontification.
