
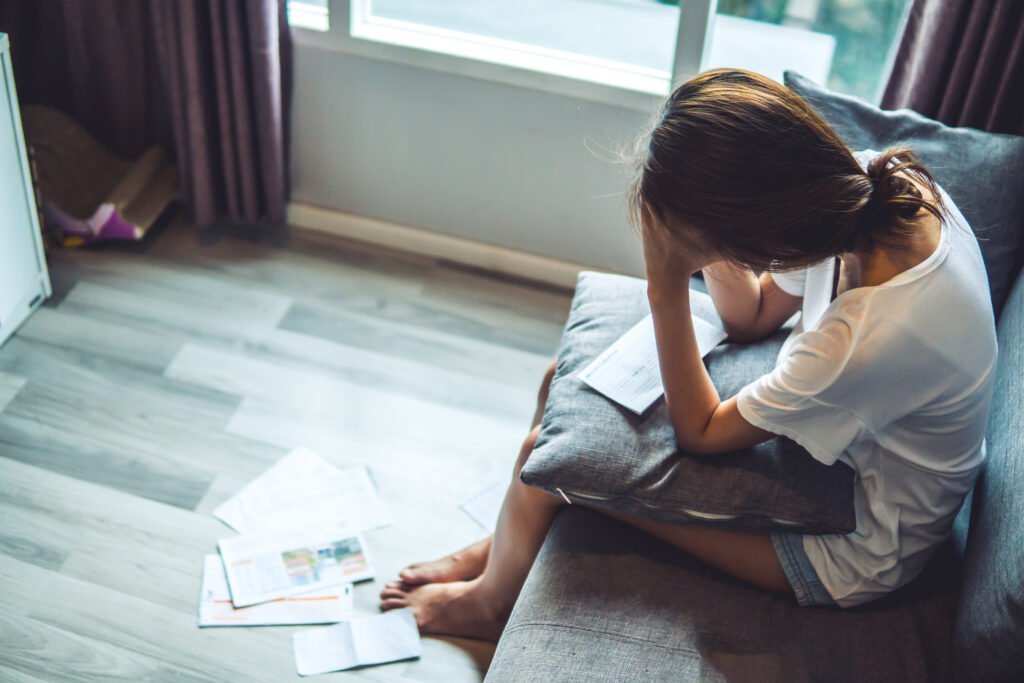
Many times when we talk about debt, we focus on numbers like bills, balances, and due dates. But the emotional weight behind them is something many people quietly deal with alone. The connection between debt and mental health can affect people of different ages and income levels.
For many people, the impact goes beyond finances. It can affect how you think, how you feel, and how you handle even simple decisions. When financial stress builds up, it can feel like you’re always carrying it with you.
In this article, we’ll explore how debt can affect mental health, why financial stress can become a difficult cycle to escape, and practical steps you can take to reduce the pressure and regain a sense of control.
How Debt Affects Your Mental Health
Nobody plans to fall behind, but life doesn’t always go as expected, and some people end up relying on debt just to get by. Living with debt can bring constant worry, mood changes, and the feeling that there’s no easy way forward.
For many Americans, financial stress is a daily reality. In the American Psychiatric Association’s 2026 Annual Mental Health Poll, 62% of adults surveyed said they were anxious about paying bills or expenses. When money worries become a regular part of your life, they can leave you feeling stressed, frustrated, anxious, or stuck.
For example, if you’re carrying a large credit card balance, you may constantly worry about making payments on time. That stress can make it harder to focus, stay organized, or make clear decisions about your finances.
The same can happen with unexpected expenses. Surprise medical bills can add financial pressure at a time when you may already be dealing with health concerns.
Warning Signs Financial Stress May Be Taking a Toll
Debt stress can weigh on your emotional well-being as much as the financial strain itself. You may notice changes in your sleep, concentration, mood, or everyday routines as stress builds.
Common signs that financial stress may be taking a toll include:
- Racing thoughts about money
- Trouble falling asleep or staying asleep
- Frequent headaches
- Difficulty concentrating
- Feeling irritable or short-tempered
- Avoiding conversations about finances
- Withdrawing from friends or family
- Feeling exhausted even after resting
When you’re facing financial hardship, it may feel like a constant weight on your emotional and physical well-being. Recognizing these signs can help you see when financial pressure is affecting more than your budget and when it may be helpful to reach out for support.
Why Dealing With Debt Can Feel So Overwhelming
Many people know they need to deal with their finances yet still struggle to take action. Debt can create fear and uncertainty, especially when you aren’t sure what will happen next.
You may worry about what a letter contains, what a creditor might say, or how much you actually owe. Some people feel embarrassed about their situation, while others blame themselves for circumstances that may have involved job loss, medical emergencies, rising living costs, or other challenges.
Those feelings can make it harder to talk openly about debt or ask for help. In turn, avoiding the situation can allow uncertainty and stress to build.
The Vicious Debt-Stress Cycle: Why It’s Hard to Break
When bills keep piling up, calls keep coming in, and you’re not sure how you’ll cover everything, financial stress can become difficult to escape. Worry may lead to avoidance, and avoidance can create new financial problems that increase the stress.
Stress leads to avoidance: The fear of facing overdue statements may make you want to look away. You might leave mail unopened or let phone calls from unknown numbers go to voicemail.
Avoidance leads to missed steps: Ignoring financial obligations can lead to missed payments, late notices, or growing balances.
Missed steps increase stress: Once a deadline is missed or a late fee is applied, the situation may feel even harder to manage, leading back to more worry and avoidance.
Breaking this cycle does not necessarily mean solving every financial problem at once. Sometimes it starts with one manageable action that reduces uncertainty.
How Debt Stress Can Affect Your Daily Life
When you’re dealing with debt, the pressure may start affecting other areas of your life. Ongoing worry can make it harder to concentrate, maintain routines, sleep well, or make everyday decisions.
Here’s a simple breakdown of some ways debt stress may affect day-to-day life:
- At work: The mental load of worrying about money may affect your ability to concentrate and perform at your best.
- In relationships: Money worries can create tension or make you pull away from friends and family because of stress or embarrassment.
- Daily routines: Stress can interfere with sleep, eating habits, and other routines, making everyday life feel harder to manage.
- Small decisions feel harder: Choices like grocery shopping or handling small expenses can feel overwhelming when your mind is already overloaded.
When Financial Stress Becomes More Than Everyday Worry
Worrying about money can be a normal reaction to a difficult financial situation. But it is important to recognize when emotional distress is persistent or begins interfering significantly with your daily life.
Pay attention if feelings of sadness, panic, or hopelessness continue for weeks, become more intense, or make it difficult to function. Frequent panic attacks, persistent feelings of worthlessness, or other serious emotional symptoms may be signs that it is time to seek professional support.
Talking with a trusted friend, family member, doctor, or mental health professional can be an important step. They may be able to provide emotional support and help you find healthier ways to cope with financial stress.
How to Deal With Debt Stress One Step at a Time
Dealing with debt-related stress often means addressing two things at once: managing the emotional pressure and taking practical steps to better understand your financial situation.
Here are some strategies that may help make the situation feel more manageable.
Organize Your Money in One Place
Start by creating a basic overview of your finances. Write down your bills, debt balances, due dates, income, and monthly expenses in one place.
A budget or simple financial overview can replace some of the uncertainty with information. Instead of trying to keep every number in your head, you can see what you’re working with and decide what needs attention first.
Start With One Small Task
When debt feels stressful, trying to fix everything at once can be overwhelming. Instead, focus on one small task.
This could be opening a bill, checking an account balance, setting a payment reminder, or making a list of what you owe. Completing one task can make it easier to identify the next step without treating the entire debt problem as something you have to solve today.
Talk to Creditors About Possible Hardship Options
Some creditors offer programs or other arrangements for customers experiencing financial hardship.
Depending on the lender and your circumstances, options may include:
- Temporary payment relief
- Adjusted due dates
- Modified payment arrangements
- Other hardship programs
Eligibility, terms, and availability vary by lender, and accommodations are not guaranteed. Still, asking what options are available can give you more information about your choices.
Ask for Support When You Can’t Do It Alone
Some people find comfort in talking with a trusted friend, family member, or counselor about what they’re going through. That person may not be able to solve the financial problem, but they can provide support while you work through it.
For example, a trusted person may be able to:
- Help sort paperwork
- Sit with you during a difficult phone call
- Help create a calendar of due dates
- Provide encouragement when you feel stuck
Sometimes simply talking about the situation can reduce the sense of isolation that financial stress creates.
Debt Relief Strategies: Ways to Manage the Financial Side of Debt
Once you have a clearer picture of what you owe, you can start looking at ways to manage the debt itself. The right approach depends on factors such as the types of debt you have, your income, your expenses, and whether you can keep up with your current payments.
Common approaches include:
- Budgeting and self-management: Adjusting spending to create more room for debt payments when your budget allows.
- Creditor hardship programs: Contacting lenders to ask whether temporary payment relief, modified terms, or other hardship arrangements are available.
- Structured debt relief options: Depending on your situation, you might explore options such as debt consolidation, credit counseling, or debt settlement. These approaches work differently and can have different costs, requirements, and potential drawbacks.
Credit Cards vs. Medical Debt: Different Debts, Different Pressures
Different types of debt can create different kinds of financial pressure. Understanding the type of debt you’re dealing with can help you identify which questions to ask and what options may be relevant.
Credit card debt: Interest charges can make it harder to reduce a balance, particularly if you’re only able to make smaller payments. If credit cards are a major source of financial pressure, learning more about credit card debt relief options can help you understand different approaches.
Medical debt: Medical bills can arrive while you’re already dealing with treatment, recovery, or other health-related costs. Some healthcare providers may offer payment plans or financial assistance programs, although availability and eligibility vary. You can also learn more about medical debt relief options.
When You May Need Help Managing the Debt Itself
Emotional support and financial support serve different purposes. If you’re struggling to keep up with several accounts, falling behind on payments, or having trouble figuring out which bills to address first, it may be useful to explore additional financial guidance.
For example, a credit counseling agency may review your finances with you and explain options such as budgeting or a debt management plan.
If medical bills are part of the problem, you can also contact the healthcare provider or billing department directly. Depending on the provider and your circumstances, payment plans, financial assistance, charity care, or other options may be available.
You don’t have to resolve every account at once. Understanding your options can help you decide which step to address first.
Know Your Rights When Dealing With Debt Collectors
Knowing some of your rights under the Fair Debt Collection Practices Act (FDCPA) and the Consumer Financial Protection Bureau’s Debt Collection Rule can make debt collection communications feel less uncertain. These federal protections limit certain practices used by debt collectors.
Limits on when, where, and how often they can contact you: Debt collectors generally cannot contact you at times or places they know are inconvenient. Regulation F also creates limits around repeated telephone calls. For example, a debt collector is presumed to violate the rule if they place more than seven calls within seven days about a particular debt or call within seven days after having a telephone conversation with you about that debt.
Right to information about the debt: Debt collectors generally must provide certain validation information either during the initial communication or within five days of first contacting you. This information can help you identify the debt, the creditor, the amount being collected, and your options for disputing it.
Protection from harassment and certain workplace contacts: Debt collectors cannot harass, oppress, or abuse you when attempting to collect a covered debt. They also generally cannot contact you at work if they know or have reason to know that your employer prohibits those communications.
What to Do When Debt Collection Calls Feel Overwhelming
It’s understandable to feel stressed when a debt collector reaches out. You may not be able to resolve the issue immediately, but taking a few practical steps can help you gather information and decide what to do next.
- Don’t rush the conversation: You don’t have to make an immediate decision simply because a collector calls. Ask for identifying information about the collector and the debt, so you know who is contacting you.
- Keep a simple record: Note dates, times, the company contacting you, and what was discussed.
- Review the validation information: Debt collectors generally must provide information that can help you recognize the debt and understand how to dispute it if you believe there is a problem.
- Set communication boundaries: You can tell a debt collector if certain times, places, or methods of communication are inconvenient. You can also ask a debt collector to stop contacting you, although doing so does not erase the debt and limited exceptions may allow additional communications.
- Report concerns if needed: If you believe a debt collector is violating federal law, you can submit a complaint to the CFPB. Your state Attorney General’s office may also provide information about protections available under state law.
Understanding your rights may remove some of the uncertainty surrounding debt collection. That can make it easier to gather information, ask questions, and decide on your next step.
Managing Debt Anxiety: When to Contact a Mental Health Professional or Crisis Support
Living with debt for a long time can be emotionally exhausting, and people respond to that pressure in different ways.
Small, consistent actions like organizing your bills and making a list of what you owe may help you feel more in control of the financial side of the situation. But if your emotional distress continues to build, your mood keeps getting worse, or financial stress is significantly interfering with your daily life, consider talking with a mental health professional.
If you or someone you know is experiencing severe emotional distress, suicidal thoughts, or a mental health crisis, call or text 988 to reach the 988 Suicide & Crisis Lifeline and connect with a trained crisis counselor.
Financial problems and emotional distress can reinforce each other. Getting support for your mental health does not require waiting until you’ve solved the financial problem first.
Final Thoughts
When debt and mental health challenges happen at the same time, the situation can feel difficult to manage. Breaking the problem into smaller steps may make it easier to see what needs your attention first.
You don’t need to address everything in one day. Start with one manageable action, whether that means reviewing a bill, organizing paperwork, asking a creditor about available options, or talking to someone about what you’re going through.
Financial and emotional support can serve different needs, and sometimes both are useful. The goal is not to solve everything immediately, but to reduce uncertainty and identify a next step you can realistically take.
